The Next SaaS Winner May Sell Fewer Seats, Not More
For much of the SaaS era, one of the nicest things about the business model was that the pricing logic matched the organisation chart.
Software helped employees do their jobs. A CRM helped salespeople manage leads. A helpdesk helped support agents manage tickets. Finance software helped accountants close the books faster.
So vendors charged per user.
The model worked because seats were a reasonable proxy for value. As a customer hired more people, it bought more licences. More employees meant more seats, more recurring revenue and, often, fairly predictable expansion for the software vendor.
AI is beginning to break that relationship.
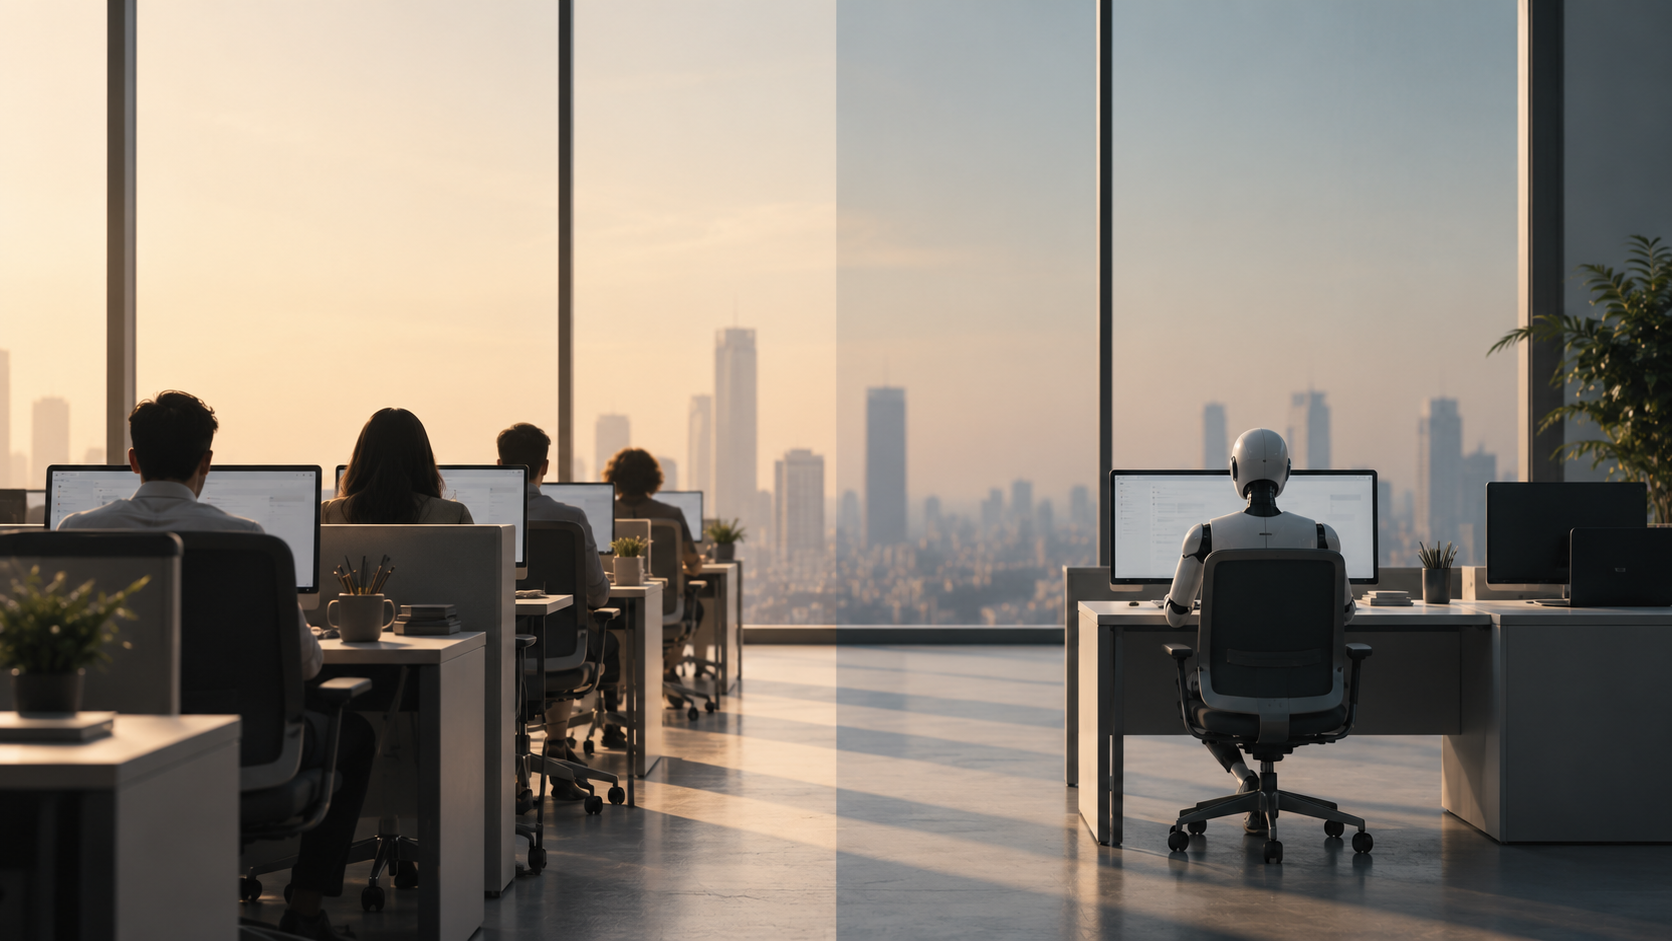
The difference is subtle but important. Traditional software largely helped a person do the work. AI can increasingly do parts of the work itself.
An agent can resolve a support query, review a document, reconcile an invoice, update a CRM record or qualify an inbound lead. Suddenly, the economically useful unit is not necessarily the number of people logging into the software. It is the amount of work getting done.
That creates a strange problem for seat-based pricing.
Imagine a customer-support team handling one million queries a year. If AI allows that company to handle the same volume with fewer human agents, the software may be creating more value for the customer while requiring fewer licences.
A vendor priced entirely by seats could therefore lose revenue precisely because its product is working.
That is a fairly fundamental inversion of the old SaaS model.
And vendors are already experimenting with what comes next.
Intercom prices its Fin AI agent from $0.99 per outcome. Zendesk measures AI-agent usage through automated resolutions. Salesforce has introduced Flex Credits that are consumed when Agentforce takes actions. Adobe uses AI credits for agent jobs, with more complex jobs consuming more credits. UiPath similarly meters agentic activity through usage units.
These models are often grouped together as “outcome-based pricing”, but there is an important distinction.
Consumption is not the same as outcome.
If a vendor charges per action, token, workflow or agent run, the customer is paying for activity. The software may succeed or fail, but the meter has still run.
True outcome pricing goes a step further. The vendor gets paid when something defined as valuable actually happens: a customer issue is resolved, a qualified meeting is booked, a claim is processed or a workflow is successfully completed.
That transfers some risk from the customer to the software company.
Under traditional SaaS, the customer pays for access whether or not employees use the product well. Under consumption pricing, it pays when the product is used. Under outcome pricing, at least in its purest form, it pays when the product works.
The closer pricing moves towards the outcome, the more attractive the proposition can sound.
It also gets much harder to implement.
What exactly counts as a “resolved” support ticket? If the customer comes back twelve hours later, was it still resolved? What makes a sales meeting qualified? If an AI agent completes 90% of a workflow before handing it to a human, who created the outcome? What happens when the agent makes a mistake?
Once pricing depends on the answer, these stop being product questions. They become commercial ones.
Pricing, after all, is partly a contract about who carries risk.
This is why the future is unlikely to be as simple as replacing every seat with an outcome.
The latest buyer data shows that tension quite clearly. Futurum's 2H 2026 survey of enterprise IT decision-makers found that, for core enterprise software, per-user pricing was the least preferred of five pricing models among buyers who considered pricing a major purchase criterion. Consumption and outcome-based models ranked higher.
But ask the same market how it wants AI sold as a separate add-on, and the answer changes. Per-user pricing was actually the most preferred model at 42.3%, ahead of consumption at 36.6% and outcome pricing at 21.1%.
Why would buyers revert to seats for AI?
Probably because predictability still has value.
A CFO may like the idea of paying only for work completed, but she also needs to know roughly what the software bill will be next quarter. A variable bill that jumps every time usage spikes creates a different problem.
Which is why the more durable model may be some form of hybrid: a recurring platform fee that pays for the underlying infrastructure, security, integrations and control layer, with a variable component linked to how much work the software performs.
There is still a revenue floor. But expansion no longer depends entirely on hiring more humans.
For an early-stage investor, that changes what is worth paying attention to.
Instead of asking only how many users a product has, one would increasingly want to know:
How much economically valuable work is the software actually performing?
Does usage expand as the customer gives it more workflows, even if the customer adds no employees?
Can that work be measured well enough to become a sensible pricing unit?
What happens to gross margins once inference, integrations, failed runs and human review are included?
As the product does more work, does it become more embedded in the customer's operating system or simply more expensive to use?
The last question may matter most.
A generic model can generate an answer. Enterprise software has to operate inside a messy organisation. It needs permissions, context, integrations, approvals, audit trails, exception handling and somebody willing to be accountable when things go wrong.
That is where an interesting moat may emerge.
The valuable AI company may not simply be the one with the best model. It may be the one a customer gradually trusts with more and more of an actual business process.
And if that happens, an old SaaS metric starts to look less useful.
For years, more seats usually meant more value.
In the next generation of software, the opposite may occasionally be true.
A customer could have fewer people using the product, spend more money on it, and still earn a much better return.
The next SaaS winner may not sell the most licences.
It may simply do the most valuable work.